Segregated vs. Omnibus Crypto Custody: What Institutions Need to Know
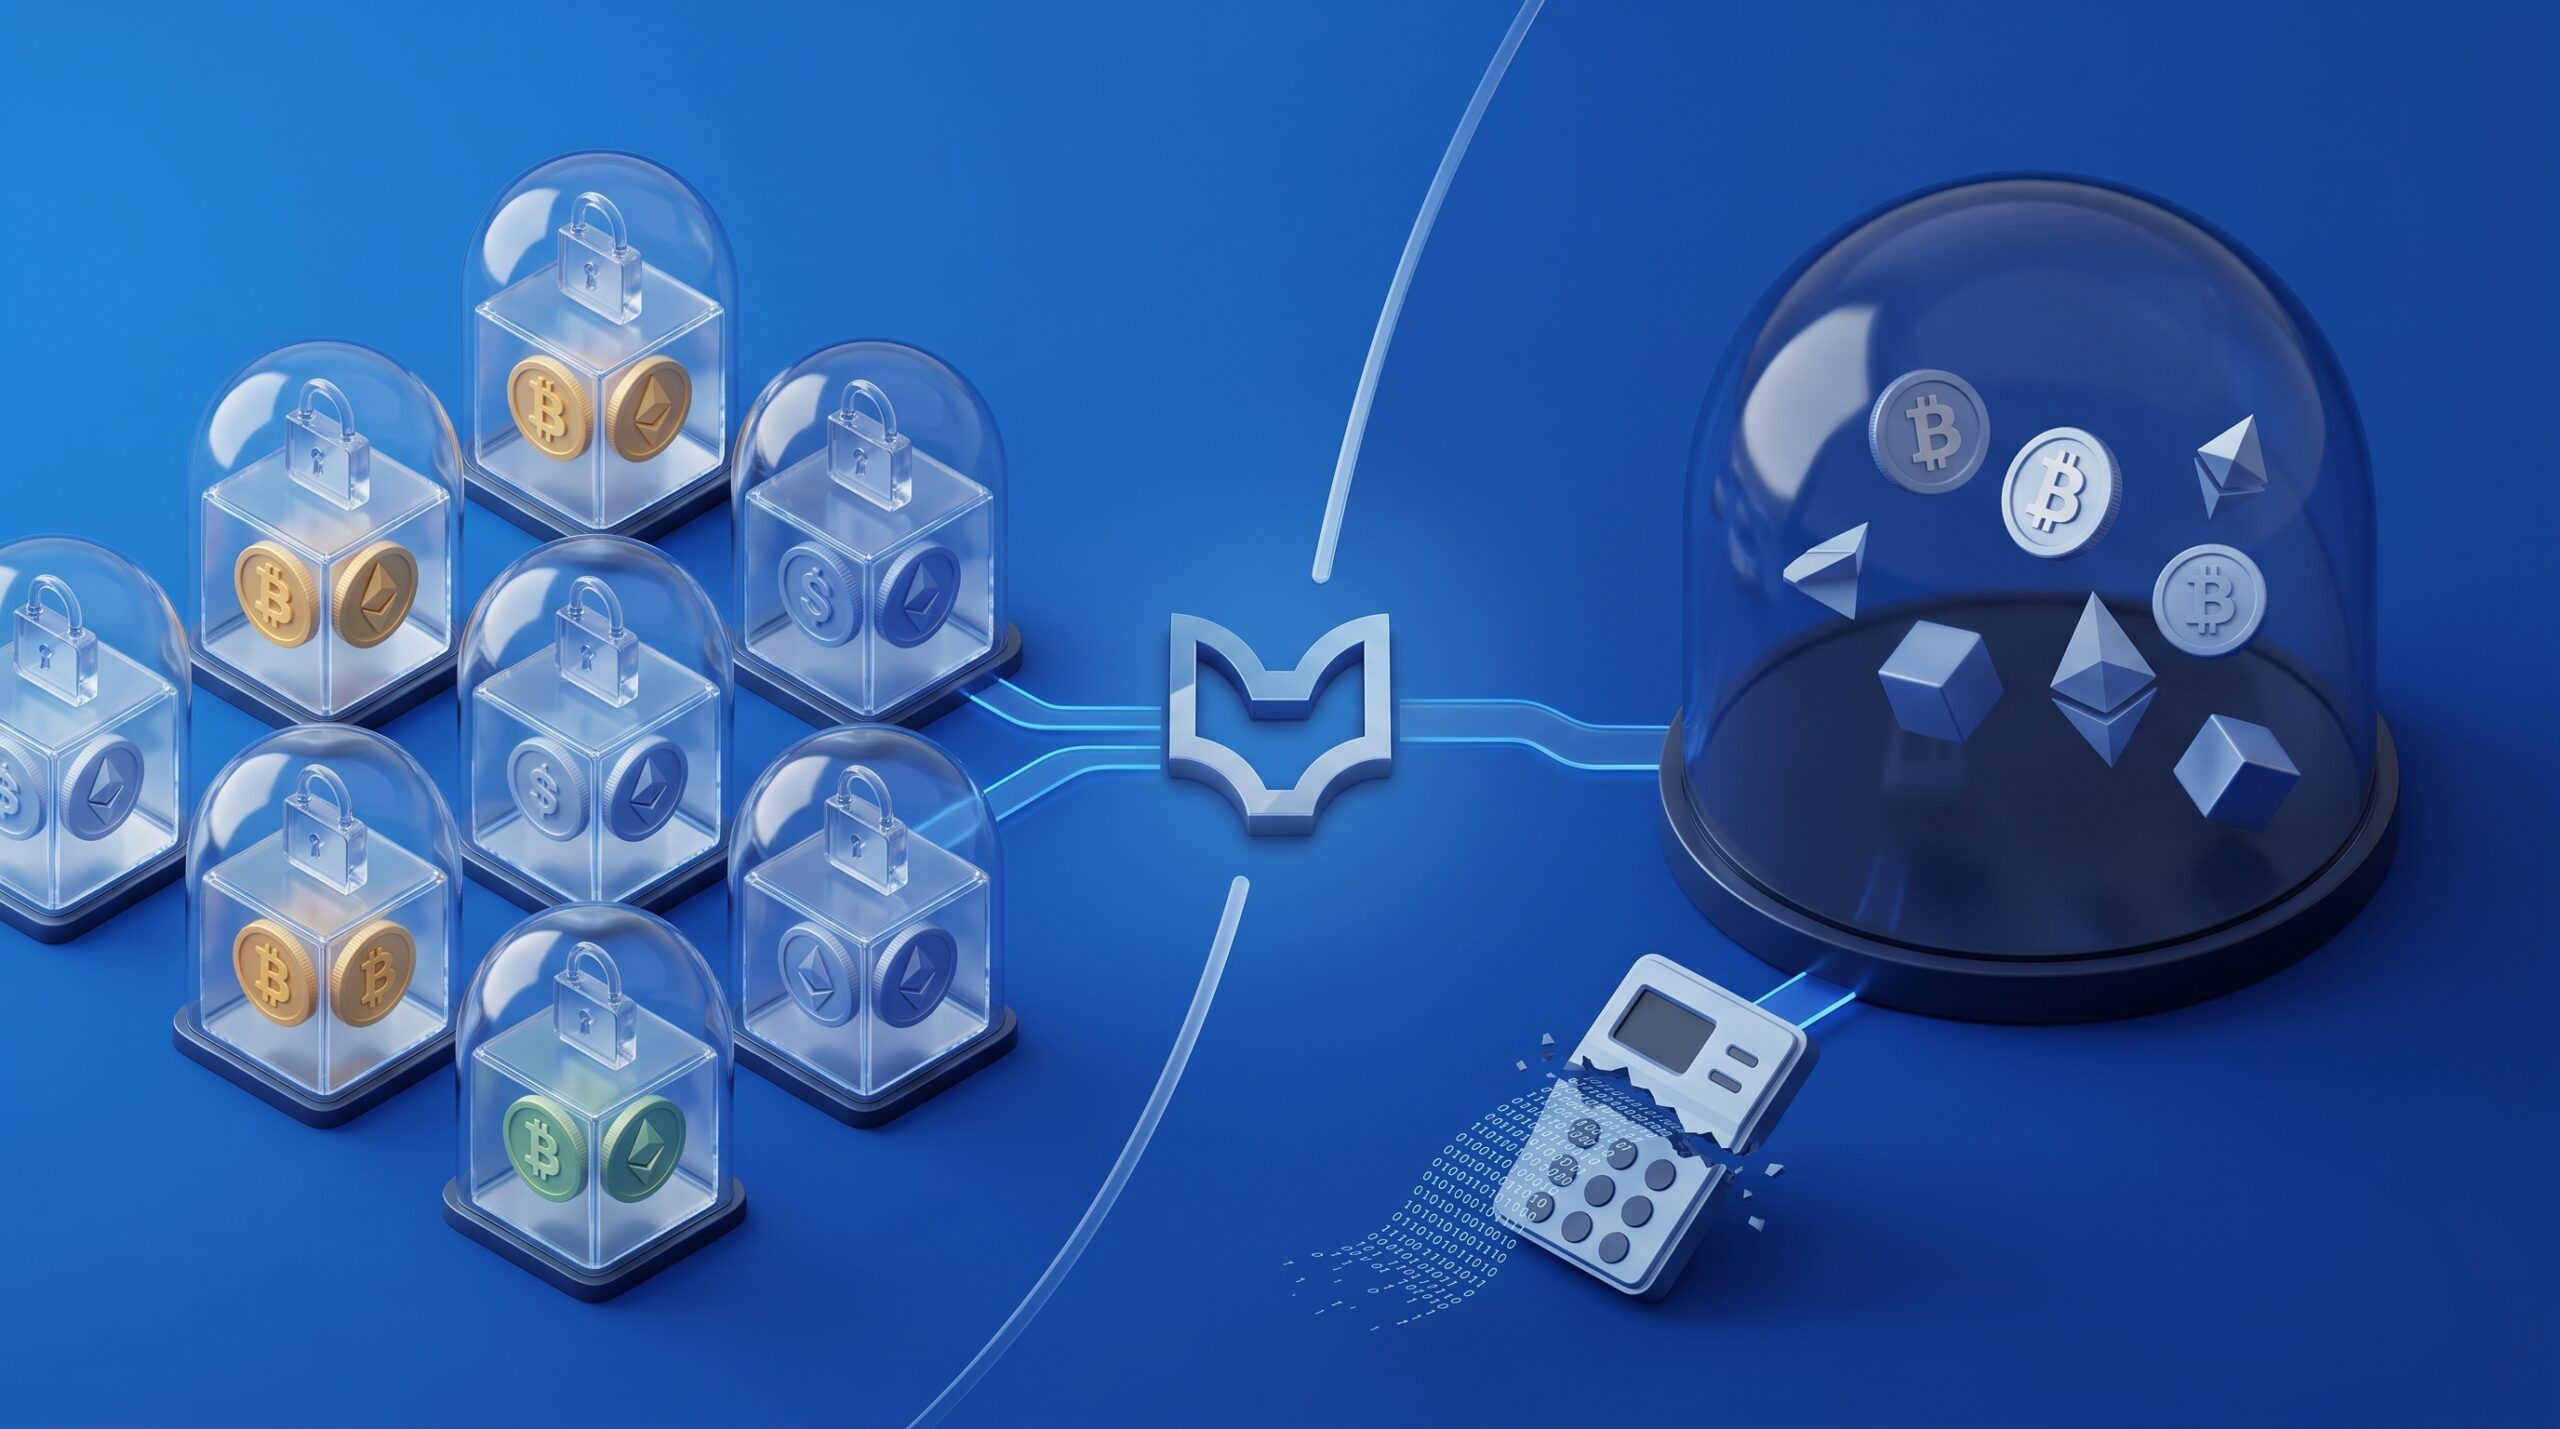
Before an institution moves meaningful size into digital assets, one question tends to come up before pricing, before execution quality, even before which venues are supported: how exactly is the custodian holding the assets, and whose assets are actually next to mine?
The answer usually comes down to one structural choice: segregated custody or omnibus custody. It sounds like a technical footnote. It isn’t. It determines what happens to your or your client’s assets if the custodian, or one of its other clients, runs into trouble.
The Basics of Segregated Custody and Omnibus Custody
At their core, both segregated and omnibus custody structures exist to safeguard client assets, but they handle ownership, accounting, and risk isolation in fundamentally different ways. Understanding the distinction between these two models is essential for evaluating counterparty risk, asset protection, and operational efficiency in digital asset management.
Segregated Custody for Digital Assets
Segregated custody means each client’s assets are held in their own distinct account, legally and operationally separate from every other client’s holdings and from the custodian’s own balance sheet. Nothing is commingled. If an institution asks “which wallet holds my assets,” a segregated structure has a specific, singular answer.
Omnibus Custody for Digital Assets
Omnibus custody means multiple clients’ assets are pooled together in a shared account structure, with the custodian maintaining internal ledgers to track which portion belongs to which client. The assets exist in the pool, and the accounting layer, not the account structure itself, is what tells you what’s yours.
Balancing Risk Profiles and Industry Legitimacy
Neither structure is inherently illegitimate. Omnibus custody is common in traditional finance and can operate securely with the right internal controls. But the two structures carry meaningfully different risk profiles, and institutions doing diligence tend to want to know which one they’re actually getting, not just which one the custodian says is safe.
Why the Difference Matters When Something Goes Wrong
The distinction is mostly invisible when everything is working. It stops being invisible the moment a custodian faces insolvency, a security incident, or a legal dispute.
Bankruptcy Remoteness
In a properly structured segregated account, client assets are titled to keep them outside the custodian’s estate, commonly using “for the benefit of” (FBO) account titling. If the custodian fails, those assets are not available to the custodian’s creditors, because they were never the custodian’s assets to begin with. Omnibus structures can achieve similar remoteness with the right legal architecture, but it depends entirely on how the pooled account is titled and documented, not just on the custodian’s internal recordkeeping.
Operational Transparency
A segregated structure gives an institution direct visibility into its own holdings, independent of the custodian’s internal ledger. In an omnibus structure, an institution is trusting that the custodian’s internal accounting is correct, reconciled, and auditable, since the on-chain or on-record reality is a pooled balance, not an individually addressable one.
Incident Containment
If a security event compromises one account in a segregated model, the exposure is contained to that account. In an omnibus model, a single point of failure in the shared account structure can, depending on how it’s engineered, put every client’s assets in that pool at risk simultaneously.
Should I Avoid Omnibus Custody for Digital Assets?
None of this means omnibus custody is disqualifying. It often comes with lower operational overhead and can be entirely appropriate for certain use cases. But it’s a different risk profile, and it deserves a different level of scrutiny during diligence than a segregated account does.
Real-World Case Study: The FTX Collapse and the Misuse of Omnibus Ledgering
When discussing segregated vs omnibus custody, it’s best to look at a real-world example to understand the potential implications. When FTX collapsed in November 2022, billions of dollars in client digital assets vanished or were locked in bankruptcy proceedings. Customers who believed they held assets on the exchange found their funds commingled with the company’s operating assets and used by its sister hedge fund, Alameda Research, to cover bad debts and risky trades.
Why Were Digital Assets Lost with the FTX Collapse?
Digital assets were lost primarily due to three key reasons:
- Commingling & Weak Internal Controls: FTX operated an omnibus custody model where client assets were held in shared omnibus wallets rather than individually segregated, on-chain addresses. Instead of maintaining strict 1:1 asset backing, FTX relied on internal database ledgers to track ownership.
- Off-Chain Record Manipulation: Because the omnibus model relied entirely on FTX’s private internal accounting rather than transparent on-chain segregation, executives could alter internal recordkeeping, extend unbacked credit lines to Alameda, and obscure massive shortfalls from customers and auditors.
- Lack of Bankruptcy Remoteness: When FTX filed for Chapter 11, the lack of clear legal titling and segregation meant customer funds became trapped in the bankruptcy estate. Customers were reduced to unsecured creditors fighting over a commingled pool of remaining assets rather than direct owners reclaiming their distinct property.
What to Actually Ask a Digital Asset Custodian
A few direct questions cut through most of the marketing language custodians use to describe their own structure:
- Is my institution’s custody account segregated or pooled with other clients, specifically, not generally?
- If segregated, is the account titled FBO, and has that structure been independently reviewed for bankruptcy remoteness?
- If omnibus, what internal controls, audits, and reconciliation processes govern the pooled account, and how often are they tested?
- Who holds legal control of the private keys or signing authority, and is that separate from whoever executes trades on my behalf?
- What happens to my assets specifically, not the pool generally, if the custodian becomes insolvent?
A custodian that answers these clearly and specifically is usually a custodian that has actually built the structure it’s describing.
Where Does sFOX’s Custody Solution Fit?
sFOX doesn’t hold custody itself. Client assets are held through SAFE Trust Company, a regulated custodian structurally and legally separate from sFOX’s trading and execution business. That separation exists specifically so that custody isn’t a function of who’s executing the trade, and so the question institutions ask first, segregated or omnibus, has a clear answer before it’s asked.
Trading, custody, liquidity, and compliance. One integration, one platform, zero compromises, and a custody structure built to answer the hardest question first.
See how sFOX separates custody from execution
Frequently Asked Questions About Digital Asset Custody
What’s the difference between segregated and omnibus crypto custody?
Segregated custody holds each client’s assets in a distinct account, separate from other clients and from the custodian’s own balance sheet. Omnibus custody pools multiple clients’ assets together in a shared account, with the custodian tracking each client’s share through internal ledgers rather than a physically separate account.
Is segregated custody always safer than omnibus custody?
Segregated custody generally offers clearer asset ownership and easier bankruptcy remoteness, but omnibus custody isn’t automatically unsafe. Its safety depends on the strength of the custodian’s internal controls, reconciliation processes, and legal structure around the pooled account. The key difference is that segregated custody makes the ownership question structurally simple, while omnibus custody makes it a matter of trusting internal recordkeeping.
What does “bankruptcy remoteness” mean for crypto custody?
Bankruptcy remoteness means client assets are legally structured to remain the client’s property and unavailable to the custodian’s creditors if the custodian becomes insolvent. This is commonly achieved through “for the benefit of” (FBO) account titling in segregated structures, though omnibus structures can achieve similar protection with the right legal documentation.
What is FBO titling and why does it matter?
FBO, or “for the benefit of,” is an account titling convention that establishes that assets are held on behalf of a specific client rather than owned by the custodian. It’s a key mechanism for keeping client assets out of a custodian’s bankruptcy estate. Institutions evaluating a custodian should confirm whether this titling is actually in place, not just assumed.
How do I know if my crypto custodian is holding my assets in a segregated account?
Ask directly, and expect a specific answer, not a general assurance. A custodian should be able to confirm whether your institution’s assets sit in their own account or a pooled structure, and if segregated, whether that account is titled FBO and has been reviewed for bankruptcy remoteness.
Does custody structure affect trading and execution?
Custody and execution are separate functions, and keeping them separate is itself a risk-management choice. When the entity executing a trade also controls custody with no independent separation, a client is exposed to that entity’s operational and counterparty risk on both sides of the same relationship, regardless of whether the underlying custody is segregated or omnibus.
What questions should an institution ask before choosing a crypto custodian?
Whether the account is segregated or pooled, how FBO titling and bankruptcy remoteness are structured, what internal controls and audits govern the custody arrangement, who holds legal control of signing authority, and what happens to a client’s specific assets, not the pool in general, if the custodian becomes insolvent.